
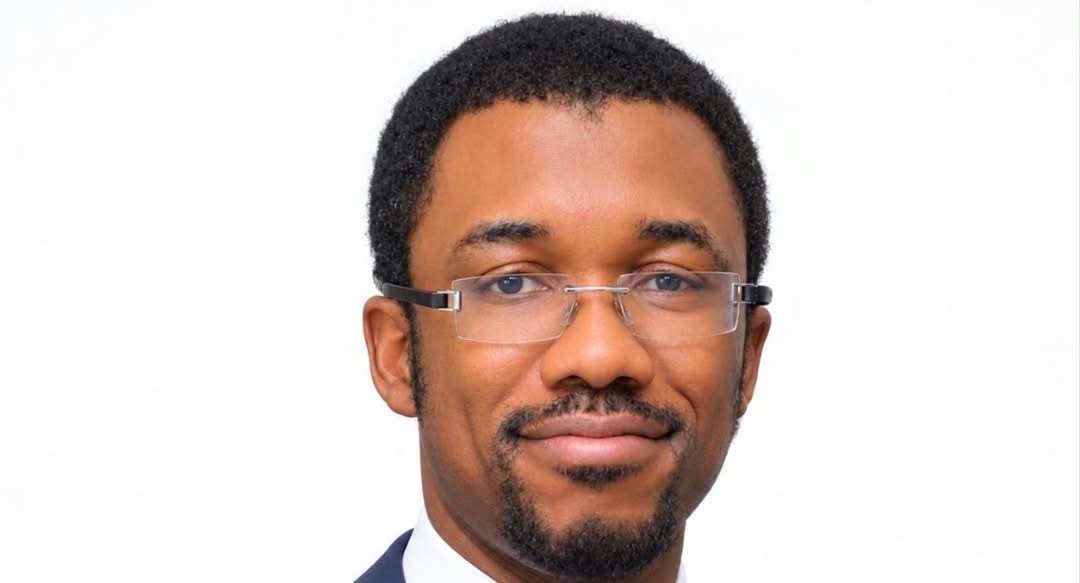
Kalu Aja, a Certified Financial Literacy Educator and seasoned Economic Analyst featured on Part 1 of Financeblog9ja’s “Nigerians Surviving Nigeria” X Space Series.
Hosted by Titilayo Mercy Babajide, the CEO of Financeblog9ja, the session highlighted practical strategies for Nigerians navigating their finances in today’s economic landscape.
Kicking off the conversation with his personal story, with his career journey, Kalu Aja shares core career insights and actionable key takeaways for everyday Nigerians.
How a Hollywood Movie Changed Kalu Aja’s Career Path from Medicine to Finance
You wanted to study medicine in University as a science student, but you have now built a successful career in finance. Can you walk us through your career journey and how you made that transition?
“I initially set out to study Medicine at the university as a science student. I wrote JAMB for Medicine, but everything changed during a Christmas holiday in my village when I watched the movie Wall Street.
I watched Gordon Gekko on screen. I didn’t understand a single word he was saying, but it sparked something in me. It was right then, I decided I wanted to learn finance in the University.
When I got to the University of Nigeria, Nsukka (UNN), I went straight to the Dean of Medicine to explain that I wanted to switch to Finance. I then met with the Dean of Finance, who reviewed my JAMB score and WAEC results, after which he admitted me to Finance Department.”
Redefining Savings in an Unstable Economy
The popular rule of thumb- “Save 20% of your income”, sounds good on paper, but in today’s economic climate, many Nigerians find it hard to save anything at all. How should we redefine saving in the current climate and what is a realistic starting point?
1. The True Purpose of Saving vs. Investing
Saving is not just about keeping money aside. The primary purpose of saving money is capital preservation, by avoiding unnecessary spending to protect your income, so as to stay afloat for inflationary pressures.
- Saving: The discipline of delaying spending today to retain value tomorrow.
- Investing: Taking those saved funds and allocating them into yield-generating assets with a clear risk profile and anticipating returns to beat inflation.
2. Turning “Active Income” into “Passive Income“
A budget details your income (active and passive) against your needs and wants to fund your financial goals. However, the ultimate objective of budgeting is not to accumulate cash in a bank account. It is to use your active income (your salary or business earnings) to gradually build passive income (returns from investments).
Instead of stressing over a rigid 20% target, focus on incremental growth:
- Start by allocating 2%, 3%, or 5% of your active income toward investments.
- Continuously increase this percentage as your cash flow optimizes.
Ask yourself these core questions regularly:
- How much of my active salary can I consistently invest to grow my passive income streams?
- What percentage of my living expenses can my passive income currently cover?
3. Overcoming the “I Don’t Earn Enough to Save” Mindset
A common misconception is that saving is reserved for high earners. In reality, data consistently shows that low-income earners often exhibit higher savings rates relative to their earnings than high-income earners who succumb to lifestyle inflation.
Whether you are a salary earner, a self-employed professional, or running a small business, financial security begins the moment you start setting aside a portion of your active income into income-generating assets. You don’t wait until you earn more to save, you save and invest to build wealth.
So stop waiting for the “perfect” time or income level to start saving. Start small at 2% to 3% to 5%…..till you get to 20%, focus on building passive income streams and build the discipline before scaling the amount.
Navigating Emergency Funds in Nigeria
Is 3 to 6 months of expenses still the right target for emergency funds or does Nigeria’s current climate call for a longer runway?
1. Differentiating Needs vs. Wants
Before calculating your emergency fund target, you must perform a strict audit of your monthly cash flow:
- Needs (Non-Discretionary Expenses): Essential costs required for basic survival including: food, rent, utilities, basic healthcare, and core transportation.
- Wants (Discretionary Expenses): Non-essential expenses including: entertainment, luxury subscriptions, and impulse purchases.
Your emergency fund should be calculated strictly based on your Needs (Essential Expenses), not your overall lifestyle spend.
2. Where to Keep Your Emergency Fund
The absolute primary objective of an emergency fund is high liquidity and fast access, not high returns.
- Keep these reserves in cash or near-cash instruments (such as high-yield savings accounts or money market funds) where the principal is secure and accessible on short notice without penalties.
- Avoid locking emergency funds into volatile or illiquid assets like real estate, equities, or long-term locked investments.
3. Target Runway: Is 3 to 6 Months Still Enough?
While 3 to 6 months remains the standard baseline, expanding your runway provides a stronger buffer against economic shocks in a country like Nigeria.
- The Starting Benchmark (3–6 Months): If your essential monthly expenses equal ₦100,000, your baseline emergency fund target is ₦300,000 to ₦600,000.
- Extending the Cushion (8–12 Months): Given Nigeria’s current economic climate, extending your fund to 8 to 12 months offers significantly greater resilience against prolonged job searches, business downtime, or unexpected inflation spikes.
4. The Golden Rule: Don’t Delay Investing
A common pitfall is pausing all investment activity until you build a 12-month emergency fund. Do not wait to complete a 12-month emergency fund before you begin investing.
Once you achieve your initial 3-to-6-month emergency fund, begin allocating surplus funds toward growth investments while gradually scaling your emergency reserve toward the 8-to-12-month target over time.
Calculate your emergency fund based only on non-discretionary essential expenses. Aim for liquidity over high yields, secure 3 to 6 months as your initial baseline and start investing while gradually expanding your runway.
Navigating Personal Loans in Nigeria
Personal loans in Nigeria have recently hit ₦2.06 trillion according to the CBN data. What would you advise on consumer loans?
1. Debt is Future Income Borrowed Today
Taking on debt means pulling your future income into the present. Every naira you borrow today is a naira (plus interest) taken away from your disposable income tomorrow. Because borrowing mortgages your future earning power, debt should strictly be used for only activities that generate new income.
2. Assets vs. Liabilities
Whether an acquisition is an asset or a liability depends entirely on cash flow generation, not the item itself:
- The iPhone Example: Purchasing a high-end smartphone purely for social status or personal communication makes it a depreciating liability. However, if that same phone is used as a core work tool for content creation, software management or direct revenue-generating business activities, it functions as an income-generating asset.
- The Car Example: Buying a car for private daily commuting incurs fuel, maintenance, and depreciation costs, making it a liability. The same vehicle deployed into a logistics fleet, ride-hailing service, or corporate rental service generates top-line revenue, turning it into an asset.
3. Differentiating Good Debt from Bad Debt
- Good Debt: Credit taken to finance income-producing assets, expand a business, or acquire skills/tools that directly increase your earning potential.
- Bad Debt: Consumer loans used to fund discretionary lifestyle expenses, luxury items, or non-essential consumption (such as funding a vacation or buying trendy wear).
Investing Your First ₦5,000,000
If you were a 30-year old Nigerian that has saved up his first 5 million, how would you save or invest it?
Crossing the ₦5,000,000 mark in savings is a major milestone for any Nigerian investor. However, how that capital should be deployed depends fundamentally on age, time horizon and long-term financial objectives.
Speaking on the strategy he would personally adopt if he were a 30-year-old Nigerian, economic analyst Kalu Aja outlined a multi-decade asset allocation framework designed to transition an investor from aggressive capital growth to sustainable passive income.
Note that this portfolio investment strategy by Kalu Aja is not a financial advice to readers, but solely for educational purposes.
1. The 30-Year-Old Strategy
At age 30, an investor’s greatest advantage is time. The primary objective at this stage should be capital appreciation by compounding interest over a long period to build wealth that outperforms inflation.
For a ₦5,000,000 portfolio at age 30, Kalu Aja would personally diversify into a high-equity, diversified asset allocation:
- 90% in Equity Mutual Funds (₦4,500,000):
- 50% in Dollar/International Equity Mutual Funds: Provides currency hedging, global diversification, and exposure to developed market equities.
- 50% in Nigerian Equity Mutual Funds: Capitalizes on domestic equity market growth and dividend yields within the local economy.
- 10% in Fixed Income & Liquidity (₦500,000):
- Allocated to government bonds, money market funds, or fixed-income mutual funds to maintain liquidity and provide baseline portfolio balance.
The Power of 3-Decade Compounding
The strategy relies on holding these positions and continuously reinvesting dividends and returns over a 30-year timeline, allowing compound growth to multiply the core principal exponentially between ages 30 and 60.
2. The 60-Year-Old Transition
As an investor nears retirement (around age 60), the portfolio’s primary goal shifts from capital appreciation to capital preservation for income stability.
- The Asset Shift: At age 60, equities become secondary. The portfolio is reallocated out of growth equities and shifted into yield-focused instruments, such as Real Estate Investment Trusts (REITs/Property ETFs), Bond ETFs and Fixed-Income Mutual Funds.
- Living off Passive Income: The predictable returns generated by these low-volatility, fixed-income assets allow retirees to fund their daily living expenses purely through cash flow and passive income without eroding their core capital.
In your 30s, focus on growth, international diversification, and equity compounding. As you approach retirement, pivot from capital appreciation to capital preservation so your accumulated wealth generates reliable passive income.
Compounding Childbirth Investment for Financial Growth
Your tweets emphasize investing for a child from birth and compounding over time. The US government now gives eligible newborns a one-time $1,000 seed through its Trump Accounts program. Can you explain how Nigerian parents and the Nigerian government can practically secure the financial future of a Nigerian child?
Kalu reaffirmed his position on childbirth investment and commended America for investing in kids through the Trump Account. Kalu also shared how he practically invested in stocks for his cousins at childbirth, while urging Nigerian parents to consider childbirth compound investment as a long-term goal.
Protecting Your Capital From Ponzi Schemes
On ponzi schemes, what three questions should anyone ask before investing in anything?
Addressing the rising prevalence of fraudulent schemes in Nigeria, economic analyst Kalu Aja outlined the critical three-question framework every investor must use to vet any financial opportunity before committing a single naira.
1. “Guaranteed” Investment
The single major sign of an investment scam is a guaranteed return from an investment.
- The Reality: In legitimate financial markets, risk and reward are inseparable. True investments, including equities, corporate bonds, real estate or commodities, fluctuate based on market dynamics, business performance, and macroeconomic conditions. No legitimate entity can guarantee performance.
- The Rule: If an opportunity pairs the word “investment” with “guarantee,” walk away immediately. Real investments carry market risk; only scams promise certainty.
2. Unreasonably High Returns
Ponzi schemes lure investors by offering outsized, unrealistic returns that sound too good to pass up. To spot an inflated promise, you must compare it against the benchmark risk-free rate.
- The Benchmark Test: Compare any proposed ROI to the yield on government instruments, such as Nigerian Treasury Bills or Sovereign Bonds (currently trading around 16% per annum).
- The Red Flag: If a business promises 10% monthly (120% annually) or 50% in a few weeks while the government risk-free rate sits at ~16% yearly, ask yourself: What underlying business model could possibly out-earn sovereign debt by such a massive margin without extreme risk? High returns without a transparent, stress-tested revenue engine are a mathematical impossibility.
3. Referral Structures and SEC Regulation
Before transferring funds, evaluate the company’s business model and legal regulatory status.
- The Referral Trap: If your payout or ability to stay onboard depends heavily on recruiting new members rather than actual underlying economic activity, you are participating in a multi-level pyramid or Ponzi structure, not an investment fund.
- The Regulatory Shield: Verify dual registration with the Securities and Exchange Commission (SEC). Both the operating company and the specific investment product must be registered, vetted, and screened by the SEC. A company having a basic Corporate Affairs Commission (CAC) business registration is not the same as holding a regulatory license from the SEC to solicit public funds.
Never let economic pressure drive you into unvetted schemes. Verify SEC registration, benchmark promised yields against the 16% risk-free rate, and treat any “guaranteed return” or recruit-to-earn model as an instant dealbreaker.
Reducing the Living Costs for Nigerians through Policies
What monetary or fiscal policy do you think will significantly reduce the living costs for Nigerians?
Highlighting a immediate mechanism for price relief, economic analyst Kalu Aja points to targeted executive intervention in import valuation as a key fiscal solution.
1. The Direct Impact of Customs FX Rates on Prices
In an import-dependent economy, the cost of landed goods, especially essential commodities like rice, sugar, and pharmaceuticals is directly pegged to the exchange rate applied by Nigeria Customs Service at the ports.
When the official import duty exchange rate tracks at elevated levels, the base cost of clearing goods rises significantly. Importers pass these higher clearing duties directly to retail consumers, driving up food inflation across local markets.
2. The Executive Mechanism: Implementing a Target Customs FX Rate
To deliver immediate consumer relief, the federal executive can issue a directive through the Ministry of Finance to benchmark a lower, fixed FX rate specifically for clearing essential imported consumables.
- The Proposal: Setting a lower concessions rate for essential goods (for instance, dropping the customs clearing benchmark rate) immediately slashes duty assessments, port clearance charges, and downstream shipping fees.
- The Consumer Benefit: Lower landed costs create immediate downward pressure on shelf prices for everyday staples.
3. The Policy Trade-Off
A key fiscal reality that accompanies this strategy is that reducing the FX rate for duty calculations reduces total government revenue generated at the ports.
However, in times of severe macroeconomic pressure, prioritizing lower living costs over maximum government extraction offers a significant socio-economic payoff. Sacrificing a fraction of customs revenue directly increases disposable household income, improves food affordability and provides real relief to millions of citizens.
Kalu Aja emphasized that curbing the high living costs does not necessarily require complex monetary tightening. Simply lowering the customs import duty FX rate on essential food imports will provide an immediate fiscal lever to reduce prices at retail markets for Nigerians.
Listen to the X Space with Kalu Aja here: