
By Toluwanimi Adejumo
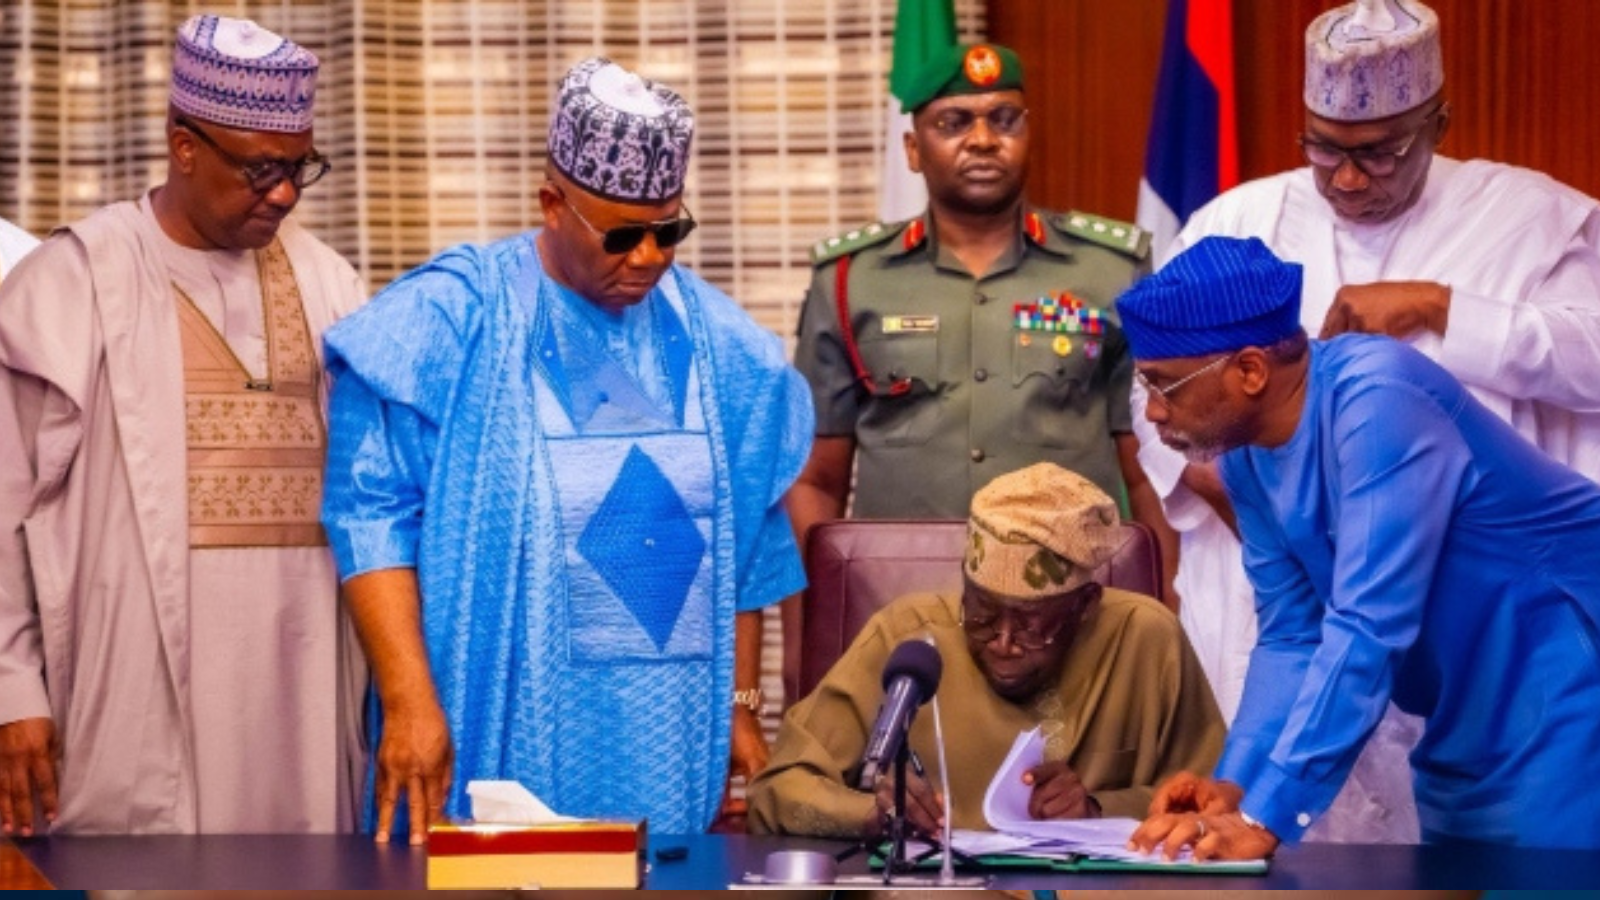
In a bid to overhaul the country’s fiscal and revenue framework, President Bola Tinubu has signed four tax reform bills into law.
The signing ceremony, held at the Presidential Villa in Abuja, marks a significant milestone in Nigeria’s economic reform agenda.
The Nigeria Government News release had earlier stated the upcoming day for the signing of the bill into law.
The Four Tax Reform Bills
The bills signed into law include:
- Nigeria Tax Bill: Aims to consolidate Nigeria’s fragmented tax laws into a harmonized statute, reducing tax duplication and enhancing the ease of doing business.
- Nigeria Tax Administration Bill: Establishes a uniform legal and operational framework for tax administration across federal, state, and local governments, fostering efficiency and uniformity in tax collection.
- Nigeria Revenue Service (Establishment) Bill: Repeals the current Federal Inland Revenue Service Act and creates a more autonomous and performance-driven national revenue agency, the Nigeria Revenue Service, with expanded responsibilities, including non-tax revenue collection.
- Joint Revenue Board (Establishment) Bill: Provides for a formal governance structure to facilitate cooperation between revenue authorities at all levels of government, introducing essential oversight mechanisms, including a Tax Appeal Tribunal and an Office of the Tax Ombudsman.
Key Highlights of the Tax Reform
The new tax laws introduce several key changes, including:
- Digital Economy Inclusion: Recognizes and introduces taxation for digital assets, online services, and fintech activities.
- Consolidation of Tax Laws: Merging various tax regulations into a single legal framework simplifies tax administration and compliance.
- Tax Incentives and Reliefs: Provisions for small businesses, exempting those with an annual turnover below ₦25 million from Corporate Income Tax.
- Withholding Tax (WHT) Adjustments: Streamlined WHT rates for various transactions.
- Removal of VAT on Rent: VAT is no longer applicable to rent-related transactions.
Tax Rates and Basis
The new tax laws also introduce changes to tax rates, including:
- Corporate Income Tax (CIT): 27.5% of taxable profits for the year of assessment 2025, and 25% from 2026 onwards.
- Personal Income Tax (PIT): Progressive tax rates, with individuals earning less than the minimum wage exempt from tax.
- Value Added Tax (VAT): 10% for the year 2025, increasing to 12.5% for 2026-2029, and 15% from 2030 onwards.
Effective Date
The new tax laws will become operational on January 1, 2026, giving stakeholders sufficient time to adjust to the changes. The Executive Chairman of the National Revenue Service (NRS), Zacch Adedeji, emphasized that implementing the reforms mid-year would disrupt fiscal coherence, and it is best to begin with the start of a new calendar year.
Implications of the Tax Reform
The new tax laws are expected to significantly transform tax administration in Nigeria, leading to:
- Increased Revenue Generation: By streamlining tax collection and reducing bureaucratic bottlenecks, the government aims to boost revenue generation and improve the business environment.
- Improved Business Environment: The reforms aim to enhance the ease of doing business, reduce taxpayer compliance burdens, and create a more predictable fiscal environment.
- Boost in Domestic and Foreign Investments: The tax reforms are expected to attract private investment and foster transparency in revenue collection, leading to increased domestic and foreign investments.
Reaction from Stakeholders
The Chairman of the Presidential Fiscal Policy and Tax Reforms Committee, Taiwo Oyedele, described the newly enacted laws as “pro-poor,” assuring that the reforms are designed to relieve financial pressure on low-income earners, small businesses, and vulnerable segments of society.
Conclusion
The signing of the four tax reform bills into law marks a significant step towards creating a more efficient and effective tax system in Nigeria.
With its comprehensive suite of reforms, the government aims to promote economic growth, reduce bureaucratic bottlenecks, and improve the business environment.
As the country embarks on this new journey, stakeholders are optimistic that the reforms will have a positive impact on Nigeria’s economy and business landscape.